Buying a home is stressful enough without the financial worry of your purchase falling through. Home Buyers Protection Insurance also known as Gazumping Insurance helps cover legal, survey and mortgage lending costs should your purchase fall through.
1 in 3 home purchases fall through, leaving many buyers hundreds of pounds out of pocket.
Cover from£78. Home Buyer Protection Insurance may reimburse some of your conveyancing fees, survey and mortgage valuation fees, and other eligible costs if your purchase falls through for a reason covered by the policy.
Gazumping Protection. The policy includes cover where the seller accepts an offer £1,000 or more higher than yours, subject to its t&cs.
No excess to pay. Standard, Plus and Premier policies have no excess. Reimbursement is subject to the applicable claim limits.
How much might I get back? The average successful claim in 2025 was £1,096. However, not every failed purchase is covered, and costs incurred before the policy starts are excluded.
Home Buyers Protection Insurance may reimburse some of your conveyancing fees, survey costs/mortgage valuation fees and mortgage/lender fees if your purchase falls through for a reason covered by the policy. Cover is subject to eligibility requirements, exclusions and claim limits. Home Buyers Protection Insurance available through our partner costs from £78.
Home Buyers Protection Insurance, also called Home Buyers Insurance or Gazumping Insurance may help you recover eligible costs if the seller withdraws or you are gazumped. If you take out Home Buyers Protection Insurance with our partners, gazumping cover applies where the seller accepts another offer at least £1,000 higher than yours. Terms, exclusions and claim limits apply.
Who can apply for Home Buyers Protection Insurance?
Home Buyers Protection Insurance is available to a wide range of buyers, including:
First time buyers
Home movers
Buy to Let investors
Second home buyers
Eligibility requirements apply; see the restrictions below.
What is the cost of Home Buyers Protection Insurance?
The cost of Home Buyers Protection Insurance starts at £78. There is no excess to pay.
Here’s a summary of what’s included in the different types of Home Buyers Protection Insurance available from our partners and how much each package costs:
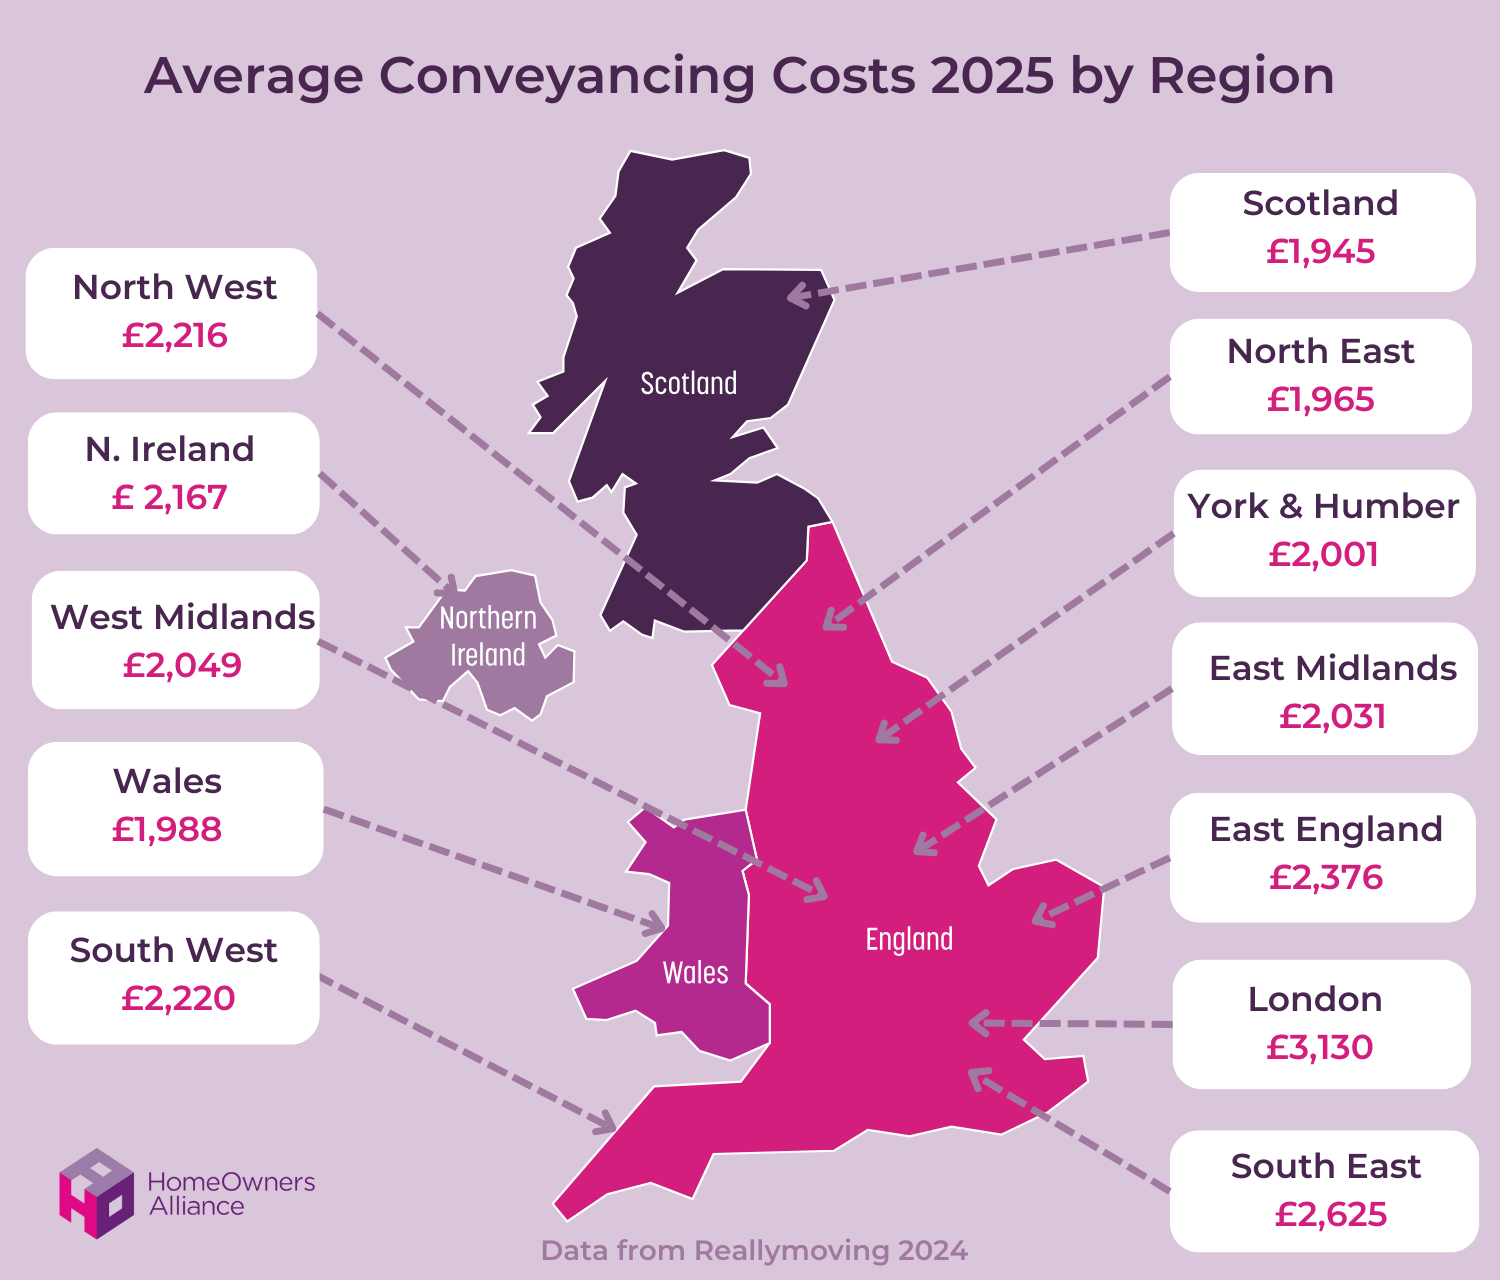
Standard Home Buyers Protection Insurance– Costs £78. Includes cover for conveyancing fees (up to £750), survey and mortgage valuation fees (up to £500) and mortgage arrangement & lender fees (up to £250). Plus, gazumping protection, if the offer accepted is at least £1000 higher than yours. You’ll pay no excess and the policy provides 120 or 180 days of cover.
Plus Home Buyers Protection Insurance– Costs £159. Includes cover for conveyancing fees (up to £1,500), survey and mortgage valuation fees (up to £750), mortgage arrangement & lender fees (up to £250), storage & accommodation (up to £300), mortgage broker fees (up to £200). Plus, gazumping protection, if the offer accepted is at least £1000 higher than yours. You’ll pay no excess and the policy provides cover for 180 days.
Premier Home Buyers Protection Insurance – Costs £209. Includes cover for conveyancing fees (up to £2,000), survey and mortgage valuation fees (up to £1,000), mortgage arrangement & lender fees (up to £350), storage & accommodation (up to £300), mortgage broker fees (up to £350). Plus, gazumping protection, if the offer accepted is at least £1000 higher than yours. You’ll pay no excess and the policy provides cover for 180 days.
When can you take out Home Buyers Protection Insurance?
If you decide you would like to buy Home Buyers Protection Insurance to protect your purchase, you can apply once your offer on a property has been accepted in writing. This is usually once you have received the memorandum of sale.
The application must be made within 14 days of formally instructing your conveyancing solicitor or submitting your mortgage application, whichever date is first, and before carrying out a house survey.
Costs incurred before the policy starts are not covered.
Home Buyers Protection Insurance vs. other home insurance types
Home Buyers Protection Insurance is different from other types of insurance you may need as a homeowner. Here’s how they compare:
Home Buyers Protection Insurance: This may reimburse eligible conveyancing, survey and mortgage fees if your purchase falls through for a reason covered by the policy.
Buildings insurance: This covers the cost of repairing or rebuilding of your house, in case there is major damage, such as a fire or falling tree.
Contents insurance: This covers damage or loss of contents, such as furniture or jewellery, in the case of fire, theft or even accidents.
Our partner offers three Home Buyer Protection Insurance packages: Standard, Plus and Premier. The table below shows you the level of cover each package provides so you can compare the options.
Insurance protection for:
Standard
Plus
Premier
Conveyancing fees
£750
£1500
£2000
Survey and mortgage valuation fees
£500
£750
£1000
Mortgage arrangement & lender fees
£250
£250
£350
Storage & accommodation
–
£300
£300
Mortgage broker fees
–
£200
£350
Gazumping protection (if offer accepted is at least £1000 higher than yours)
Home Buyers Protection Insurance cover insured events
It’s important to know when your cover will kick in. Home Buyers Protection Insurance covers you if one of the following insured events occurs and the policy’s conditions are met:
The property owner withdraws the house from the market
The property owner receives and accepts an offer which is at least £1,000 greater than the offer they have accepted from you
Local authority search indicates the property is subject to a compulsory purchase order
The vendor is not legally entitled to sell the property
The mortgage property valuation is less than 90% of the accepted offer
The mortgage lender applies a retention on the loan which is more than 10% of your accepted offer
Rectification work is required to the property by the mortgage lender and the cost exceeds 10% of the accepted offer amount
The property is damaged during the period of cover and it costs more than 10% of the property value to repair
Redundancy or employment relocation that meets the policy’s definitions and conditions. Voluntary redundancy is excluded.
Restrictions to cover:
Property type: The property must be in England, Wales or Northern Ireland and be of permanent construction. The policy holder must be over 18 years of age. You must also use a solicitor or licensed conveyancer to conduct the conveyancing of the property.
Timing: You cannot be reimbursed for costs incurred before the policy start date. You must not have had a survey carried out on the property before the policy start date. You’ll also not be covered if you deliberately cause a delay which causes the house purchase not to complete.
Purchase type: The purchase of the property must not be subject to a contract race or sealed bids. Best and final offers fall within the same category as sealed bids.
Knowledge of problems: You won’t be covered if you knew that the house purchase would not complete before you bought Home Buyers Protection Insurance. The policy also excludes circumstances where you are aware of a survey carried out on the property in the 90 days before cover starts that may give cause for the purchase to fail.
General exclusions: You won’t be covered if you withdraw from the house purchase for reasons not covered by the policy (you can’t just change your mind for instance), where you are able to obtain a refund on your fees, or in the case of redundancy, if you took voluntary redundancy, are self-employed or are a company director or partner of the company giving notice of redundancy.
This is a summary of restrictions, rather than the full policy wording. Check the provider’s policy documents for all conditions and exclusions.
Get Home Buyers Protection Insurance
Home Buyers Protection Insurance available through our partner provides cover for conveyancing, mortgage and survey fees incurred by an insured purchaser when their purchase of a property falls through for an insured reason.
The average payout among successful claims in 2025 was £1,096 for buyers who took out the insurance through HomeOwners Alliance.
With many reasons causing a property purchase to fall through, no one likes being left to foot the bill for the wasted costs. By helping reimburse eligible fees, Home Buyers Protection Insurance can offer peace of mind should the purchase not go ahead for a reason covered by the policy.
If you’re considering Home Buyers Protection Insurance, check the application deadline once your offer is accepted, as there are some steps in the home buying process after which, you will not be able to take out a policy.
Here are answers to frequently asked questions asked by people who have applied for home buyers protection insurance. These are meant as general guidance when purchasing the insurance but terms and conditions apply, so you should check the full policy wording prior to purchase.
Frequently Asked Questions:
Is it too late if I have already submitted my mortgage application?
You can still apply to take out cover as long as you do so within 14 days of submitting your formal mortgage application or instructing your conveyancing solicitor, whichever happens first.
What if I have a ‘mortgage in principle’?
Getting a mortgage in principle is different to making a mortgage application. A mortgage in principle is an indication that a lender could lend you a specified amount, based on details you’ve provided about your income, spending and debt. You can get a mortgage in principle at any time and it’s advisable to get one before you start house-hunting so that you can show estate agents you’re a serious buyer.
However, you can only make a full mortgage application once you’ve had an offer accepted on a house. And you can apply to take out Home Buyers Protection Insurance as long as your application is made within 14 days of applying for a mortgage or formally instructing your conveyancing solicitor, whichever happens first. A mortgage in principle does not start this 14-day window.
I have already instructed my solicitor/ conveyancer, am I still eligible?
You can still apply to take out cover as long as you formally instructed your solicitor within the past 14 days. This is the formal instruction to act once you have confirmation of the offer.
Note that you must apply for cover within 14 days of submitting your formal mortgage application or instructing your conveyancing solicitor, whichever happens first.
Can I take out cover if I already have had a survey carried out?
Unfortunately, no.
Am I covered if I have a bad survey on the property?
Having a bad survey report on its own does not meet an insured event and will not be covered. However, if the circumstances meet an insured event, for example a mortgage valuation of less than 90% of the accepted offer, then you may be able to claim, subject to the policy terms and conditions.
What about a property that is repossessed or I’m buying it at auction?
No – if you’re buying a repossessed property or at auction where you are required to complete within 28 days, the policy does not provide cover because of the increased risk of the purchase failing within the limited time available.
Am I covered for the deposit I have to pay to secure the property?
No
Can I transfer the cover to another property if the first purchase falls through?
No – the policy only covers the property that you are buying at the start of the policy.
I’m buying a property at auction – am I eligible for cover?
No – auction properties pose separate risks that Home Buyers Protection Insurance is not designed to cover.
Am I covered for legal fees on the property that I am selling, as well as, the property I am looking to buy?
No. The policy only covers costs related to the property that you are buying. Separate home seller’s protection insurance may be available if this cover is required.
Can you buy Home Buyers Protection insurance as a limited company?
Yes. you can buy the policy as a limited company. When you complete the online form to purchase the insurance, select ‘No’ to the first question on the application, ‘Is there a joint applicant purchasing the property with the main policyholder?’, the next question will then appear as ‘Is the property to be insured under this insurance be in the name of a company?’, to which you can select ‘Yes’ and input the company name.
With 1 in 3 property purchases falling through, Home Buyers Protection Insurance can help you protect some of your hard earned money. It may reimburse you some of what you would have already spent on the cost of a house survey, conveyancing and mortgage fees if your purchase falls through for a reason covered by the policy.
Whether it is worth it for you depends on the premium, the costs you could lose and the cover available. Check the limits and exclusions, along with any protection you already have.
What protection policies do I need when buying a house?
Home Buyers Protection Insurance is one option for reducing the financial impact of a failed purchase. It may help you recover costs if you are gazumped, or if the seller simply changes their mind and decides not to proceed, where the circumstances are covered by the policy.
When buying a home, other types of cover you may consider include life insurance, mortgage protection insurance, income protection, critical illness cover, buildings insurance and contents insurance. Buying a house is likely to be one of the biggest investment you’ll make. Take the time to check you have the right level of cover for you.
Can a seller pull out of a house sale?
Yes. According to 2022 research by the House Selling Expert, the most common reason for a house sale falling through is a change of heart or circumstance. If you’re buying and the seller has pulled out before the exchange, this can leave you seriously out of pocket. Home buyers protection insurance from £78 may help reduce your financial loss by reimbursing some of your costs, provided the reason for the seller’s withdrawal is covered by the policy.
HomeOwners Alliance Ltd is registered in England, company number 07861605. Information provided on HomeOwners
Alliance is not intended as a recommendation or financial advice.
HomeOwners Alliance Ltd is an Introducer Appointed Representative of Mortgage Advice Bureau (Derby) Limited which is authorised and regulated by the Financial Conduct Authority.
If you take out a mortgage or protection product through Mortgage Advice Bureau, they pay us a referral fee of 25%. You are not obliged to use their services.
HomeOwners Alliance Ltd is an Introducer Appointed Representative (IAR) of LifeSearch Limited, an Appointed
Representative of LifeSearch Partners Ltd, authorised and regulated by the Financial Conduct Authority. (FRN:
656479).
Independent Financial Adviser service is provided by Unbiased, who match you to a fully regulated, independent
financial adviser, with no charge to you for the referral.
HomeOwners Alliance Ltd is an Introducer Appointed Representative (IAR) of Fluent Money Limited, which is authorised and regulated by the Financial Conduct Authority. Calls may be monitored/recorded.
HomeOwners Alliance Ltd is an Introducer Appointed Representative (IAR) of Rhino Protect Limited which is authorised and regulated by the Financial Conduct Authority.