


Find the best estate agent near you Start here
Bridging loans can help if you need funds quickly, for example if you’re buying a property before selling your current home. We explain how they work, the costs, risks and when they may be suitable.


A bridging loan is a short-term secured loan that helps bridge a temporary funding gap, usually until money from a property sale or longer-term finance becomes available.
KEY INFORMATION

Jump to: How bridging loans work | How to get a bridging loan | How much bridging loans cost | Bridging loan calculator | Alternatives to bridging loans | FAQs
Bridging loans provide short-term finance secured against property. Before the loan is agreed, you’ll need to show the lender how you plan to repay it – this is known as your exit strategy. The loan is then repaid once your exit strategy is completed, usually by selling a property or remortgaging.
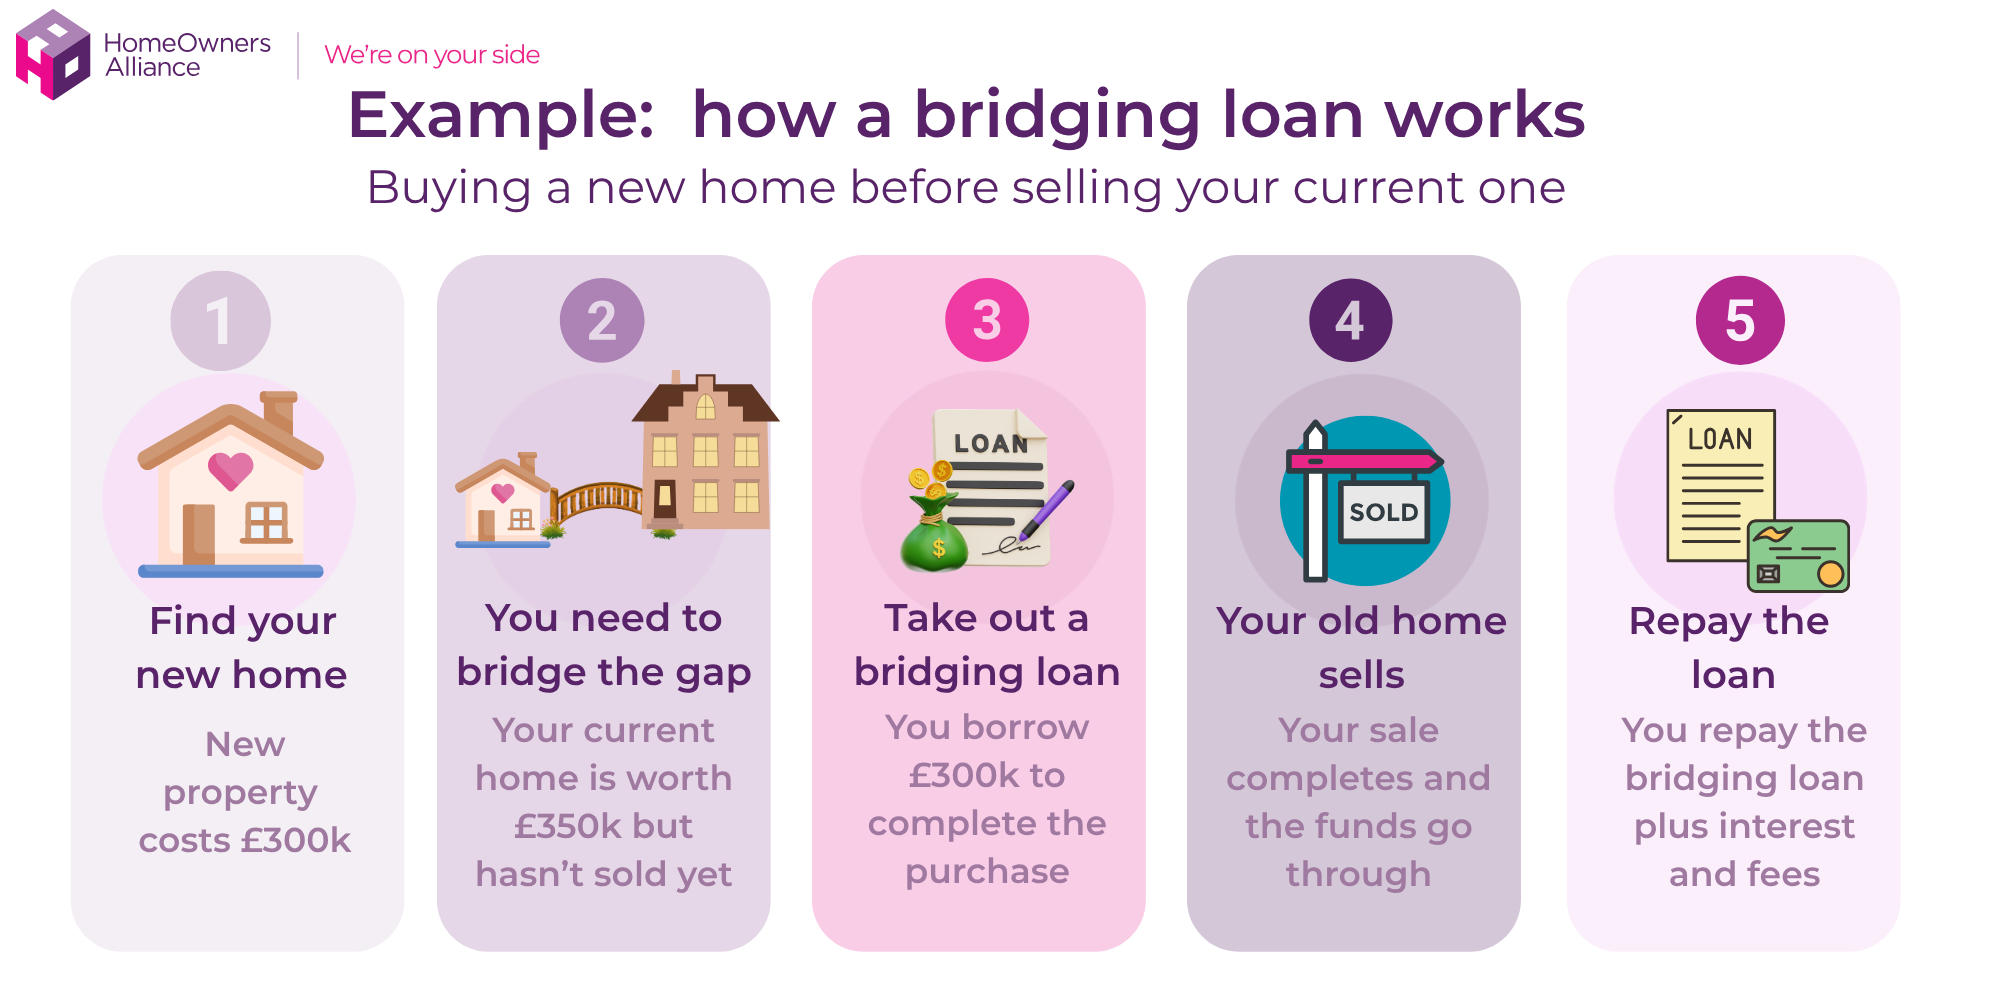
In simple terms, bridging loans work as follows:
Here’s an example of how a bridging loan works if you own your property outright. The same principle applies if you already have a mortgage, although the amount you can borrow will depend on the equity available.
Bridging loans can be used in a range of situations where you need short-term finance quickly. Common examples include:
Not sure if a bridging loan is right for you? Get specialist advice today.
Our specialist bridging loan partners can discuss your personal circumstances and find you a competitive bridging loan
Think carefully before securing other debts against your asset. Your asset may be repossessed if you do not keep up repayments on a mortgage or any debt secured on it. The actual rate and fees charged will depend upon your circumstances. Ask for a personalised illustration.
You can typically borrow between £50,000 and £10 million with a bridging loan, although this varies between lenders. The amount you can borrow depends mainly on the value of your property, the equity available and your exit strategy.
Bridging loans are often available up to around 75% loan-to-value (LTV), although this varies by lender and your circumstances. In some cases, you may be able to borrow up to 100% of the purchase price if you can provide additional security. If you already have borrowing secured against the property, this will also affect how much you can borrow.
Not sure what your loan-to-value (LTV) is? Use our Loan to Value calculator.
You may be able to get a bridging loan if you have enough equity in a property and a clear plan for repaying the loan. Whether you’ll qualify depends on your circumstances and the lender’s criteria.
Bridging loans may be available if you’re:
When deciding whether to lend, providers will usually consider:
Our specialist bridging loan partners can discuss your personal circumstances and find you a competitive bridging loan
Think carefully before securing other debts against your asset. Your asset may be repossessed if you do not keep up repayments on a mortgage or any debt secured on it. The actual rate and fees charged will depend upon your circumstances. Ask for a personalised illustration.
Here’s the process of how to apply for and arrange a bridging loan:
A specialist bridging loan broker can compare lenders and help find a loan that suits your circumstances. They’ll ask why you want a bridging loan, how much you need to borrow and how you plan to repay it.
Your exit plan may be selling a property or, if you’re buying an unmortgageable property, renovating it before taking out a residential or Buy to Let mortgage.
Bridging loans are specialist finance, so choosing the right broker can make a big difference. A good broker will compare lenders, explain the costs and help you understand whether a bridging loan could be suitable for your circumstances.
When comparing brokers, consider:
Once your bridging loan broker understands your needs, they’ll speak to lenders on your behalf. If you use specialist bridging loan broker Fluent Money, they may be able to negotiate rates that aren’t widely available. Fluent Money also has dedicated underwriting support from some larger lenders, which can help with more complex bridging cases.
Once you’ve chosen a lender, they’ll complete the application with detailed information about the property and your financial circumstances.
The lender will assess your application against their lending criteria and arrange a valuation of the property being used as security.
While lending criteria vary, they’ll typically consider:
You’ll also normally need to provide documents to support your application (see more information below).
Once these checks have been completed, the lender may make a conditional offer setting out the loan amount, interest rate, fees and terms.
Bridging loans require several legal steps and it’s important to use a solicitor or conveyancer experienced in dealing with bridging finance. Your broker will explain what’s involved and help coordinate the process. Once legal checks are complete and all conditions are met, the lender will formally approve the loan.
Once everything has been approved, the lender releases the funds (sometimes called drawdown).
Get a free, no obligation quote and instant decision from specialist brokers Fluent Money.
Some bridging loans can be arranged in a matter of days, while more complex transactions can take six to eight weeks. How long it takes will depend on your circumstances and the lender.
Factors that could affect how long it takes include:
Bridging loans are mainly offered by specialist lenders rather than high street banks, although some building societies also offer bridging finance. Before the 2008 financial crisis, some high street banks offered bridging loans, but the market has since become much more specialist.
Many borrowers use a specialist broker because they can compare options from different lenders, explain the costs and help you understand whether a bridging loan could be suitable for your circumstances.
If a bridging loan isn’t the right solution, a good broker should also explain any suitable alternatives.
The exact documents required vary between lenders, but you’ll usually be asked to provide:
You may need to supply additional documents depending on your circumstances but your bridging loan broker will explain what you need to provide.
Our specialist bridging loan partners can discuss your personal circumstances and find you a competitive bridging loan
Think carefully before securing other debts against your asset. Your asset may be repossessed if you do not keep up repayments on a mortgage or any debt secured on it. The actual rate and fees charged will depend upon your circumstances. Ask for a personalised illustration.
The total cost of a bridging loan includes interest and a range of fees, so it’s important to compare the overall cost rather than the interest rate alone.
Alongside the interest rate, there are other bridging loan fees you may have to pay. These include:
Want a personalised estimate? Use our free Bridging Loan Calculator to estimate the interest, fees and total cost based on your own circumstances.
This example shows how much a bridging loan could cost. It’s for illustration only – your costs will depend on the lender, interest rate, fees and how long you need the loan.
| Bridging Loan Borrowed | £250,000 |
| Monthly Interest Rate | 0.75% |
| Interest Amount | £5,781 (Assumes full term of 3-months, calculated daily) |
| Arrangement fee | £5,000 (Added to loan) |
| Valuation Fee (Inc. VAT) | £348 (Some lenders provide valuations using an Automated Valuation Model – AVM at no charge) |
| Telegraphic Transfer Fee | £35 (Added to loan) |
| Administration Fee | £145 (Added to loan) |
| Estimated legal costs | £900 |
| Redemption Administration Fee | £40 |
| Total cost | £262,249 |
So in this example, the interest and fees add around £12,249 to the £250,000 originally borrowed.
Our specialist bridging loan partners can discuss your personal circumstances and find you a competitive bridging loan
Think carefully before securing other debts against your asset. Your asset may be repossessed if you do not keep up repayments on a mortgage or any debt secured on it. The actual rate and fees charged will depend upon your circumstances. Ask for a personalised illustration.
Bridging loan interest rates are usually quoted as a monthly rate rather than an annual percentage rate (APR). Many lenders calculate interest daily, but how and when you pay it depends on the type of loan you choose.
| Interest payment option | How this works |
| Serviced (Monthly) | You pay the interest each month and it is not added to the loan. This works in a similar way to an interest-only mortgage. |
| Rolled up | Interest is added to the loan balance and repaid when you repay the bridging loan. |
| Retained | You borrow the interest upfront for an agreed period and then when the loan is paid back, any unused interest is returned to you. |
Bridging loan interest rates in the UK vary, depending on the lender, loan-to-value, property type and your exit strategy.
A specialist bridging loan broker can compare lenders and explain the interest rates, fees and payment options available. Plus, the brokers at Fluent may be able to negotiate rates not readily available in the wider market.
Get a free, no-obligation initial consultation.
Our specialist bridging loan partners can discuss your personal circumstances and find you a competitive bridging loan
Think carefully before securing other debts against your asset. Your asset may be repossessed if you do not keep up repayments on a mortgage or any debt secured on it. The actual rate and fees charged will depend upon your circumstances. Ask for a personalised illustration.
Use this bridging loan calculator to get a detailed estimate of the interest, fees and total cost of a bridging loan based on your circumstances. You can then speak to a specialist broker for advice and a detailed quote.
A bridging loan could be a good option if you need fast, short-term finance and have a clear plan to repay it. However, they’re generally more expensive than standard mortgages and won’t be suitable for everyone. Before applying, make sure you’ve considered the costs, risks and any alternative ways of borrowing.
Bridging loans can be a useful short-term solution in the right circumstances, but they’re not suitable for everyone. Before applying, weigh up the benefits, costs and risks.
| Pros of bridging loans | Cons of bridging loans |
|---|---|
| Speed: Funds can often be available much more quickly than with a standard mortgage. | Your property is at risk: Because the loan is secured against property, you could lose it if you can’t repay the loan. |
| Large loan amounts: It may be possible to borrow substantial sums, depending on the value of your property and your circumstances. | Higher borrowing costs: Interest rates and fees are generally higher than standard mortgages. |
| Flexibility: Bridging loans can help solve short-term funding gaps, such as buying before selling or completing on an auction purchase. | Additional costs: Arrangement, valuation and legal fees can increase the overall cost. If you buy before selling your existing home, you may also have to pay higher Stamp Duty rates upfront. |
| Access to finance: Specialist lenders may consider properties that mainstream mortgage lenders won’t. | A clear exit strategy is essential: You need a realistic plan for repaying the loan. |
The right type of bridging loan depends on your circumstances, particularly whether you already have a mortgage and how you plan to repay the loan.
There are several types of bridging loan. The main differences are whether the loan takes first or second charge over your property, whether the interest rate is fixed or variable, and when you’ll need to repay the loan.
Because bridging loans are secured against property, a legal charge is placed against your home.
| Own your home outright | Own your home with a mortgage | |
| Can I get a first charge bridging loan? | Yes, if you meet the lender’s criteria. | Possibly, if the bridging loan is used to repay your existing mortgage. Otherwise, a second charge loan may be used. |
| Second charge bridging loans | You don’t need to take out a second charge loan as you can take out a first charge one, if you can meet the lender’s criteria. | Yes, if you meet the lender’s criteria. |
Most bridging loans have a fixed monthly interest rate, although some lenders offer variable rates.
The main difference between an open and closed bridging loan is when you agree to repay it.
| Open bridging loans | Closed bridging loans | |
| When can I pay back my bridging loan? | No fixed repayment date, although the loan must still be repaid within the lender’s agreed term. Lenders usually require you to repay within 12 months but some lenders offer longer repayment terms. | You’ll have a fixed repayment date. |
Some bridging loans are regulated by the Financial Conduct Authority (FCA), while others are not.
Regulated loans come with FCA consumer protections that do not apply in the same way to unregulated bridging loans. A specialist broker can explain which rules apply to your circumstances.
Our specialist bridging loan partners can discuss your personal circumstances and find you a competitive bridging loan
Think carefully before securing other debts against your asset. Your asset may be repossessed if you do not keep up repayments on a mortgage or any debt secured on it. The actual rate and fees charged will depend upon your circumstances. Ask for a personalised illustration.
A bridging loan isn’t always the right solution. Depending on your circumstances, another type of borrowing may be cheaper or more suitable. Here are some alternatives to consider.
If you don’t need to complete quickly, remortgaging may be a cheaper alternative to a bridging loan.
Remortgaging may be suitable if:
A bridging loan may be more suitable if:
If you’re considering a bridging loan because you want to buy a new home but you’re struggling to sell your existing home, a Let to Buy mortgage may be an alternative. Let to Buy means you’ll have two mortgages: you’ll need a Let to Buy mortgage for your current property and take out a standard residential mortgage for the property you want to buy.
Pros
Cons
Find out more in our guide Let to buy mortgages explained.
A secured homeowner loan could be suitable if you need to borrow against your home but don’t need the speed or flexibility of a bridging loan. Like a bridging loan, your home could be at risk if you don’t keep up repayments.
If the amount you want to borrow on a bridging loan is relatively small, you may prefer a personal loan because it doesn’t require your property as security. However, the amount you can borrow is usually much lower.
| If you want to… | You could consider… |
| Buy before selling | Bridging loan |
| Release money from your home | Remortgage |
| Keep your current home and rent it out | Let to Buy |
| Borrow a smaller amount | Personal loan |
| Borrow against your home without moving | Secured loan |
Our specialist bridging loan partners can discuss your personal circumstances and find you a competitive bridging loan
Think carefully before securing other debts against your asset. Your asset may be repossessed if you do not keep up repayments on a mortgage or any debt secured on it. The actual rate and fees charged will depend upon your circumstances. Ask for a personalised illustration.
Yes, you may still be able to get a bridging loan if you have bad credit. Lenders will consider your credit history alongside factors such as the property you’re using as security, the equity available and your exit strategy. However, poor credit may reduce the number of lenders available to you or increase the cost of borrowing.
If you do have bad credit, it’s a good idea to do everything you can to improve your credit score – find out how to do this in our guide on 11 Tips to improve your credit score for a mortgage.
Yes. Bridging loans are typically more expensive than a traditional mortgage. Interest rates are usually higher and you may also need to pay arrangement, valuation, legal and other fees. Bridging loans are designed for short-term borrowing, so it’s important to compare the total cost rather than just the interest rate.
Find out more about costs with our Bridging loan calculator.
You usually repay the bridging loan when your exit strategy is completed, for example when you sell a property or take out a mortgage. How you pay the interest depends on the loan: you may pay it monthly, have it added to the loan and repay it at the end, or have the interest calculated and included upfront so you don’t make monthly interest payments.
Yes, bridging finance can be used to buy a Buy to Let property, including one that needs renovation before you can get a standard Buy to Let mortgage. You’ll need a clear plan for repaying the bridging loan, such as selling the property or switching to a Buy to Let mortgage.
Yes, bridging loans are commonly used for house purchases, particularly when there is a gap between buying a new property and selling your existing one.
For example, a bridging loan could allow you to complete on your new home before your existing property has sold or help keep your purchase on track if your property chain breaks down.
However, you’ll need a clear exit strategy, such as selling your current home or taking out a mortgage.
There is no real difference between a bridge loan and a bridging loan – they refer to the same type of short-term property finance. ‘Bridging loan’ is the term generally used in the UK, while ‘bridge loan’ is more commonly used in the US.
Not in the same way as a standard mortgage. Instead, lenders usually look at the value of the property you’re using as security and how much equity you have.
Bridging loans are often available up to around 75% loan-to-value (LTV). In some cases, you may be able to borrow up to 100% of the purchase price if you can provide an additional property as security.
HomeOwners Alliance Ltd is registered in England, company number 07861605. Information provided on HomeOwners Alliance is not intended as a recommendation or financial advice.
HomeOwners Alliance Ltd is an Introducer Appointed Representative of Mortgage Advice Bureau (Derby) Limited which is authorised and regulated by the Financial Conduct Authority.
If you take out a mortgage or protection product through Mortgage Advice Bureau, they pay us a referral fee of 25%. You are not obliged to use their services.
HomeOwners Alliance Ltd is an Introducer Appointed Representative (IAR) of LifeSearch Limited, an Appointed Representative of LifeSearch Partners Ltd, authorised and regulated by the Financial Conduct Authority. (FRN: 656479).
Independent Financial Adviser service is provided by Unbiased, who match you to a fully regulated, independent financial adviser, with no charge to you for the referral.
HomeOwners Alliance Ltd is an Introducer Appointed Representative (IAR) of Fluent Money Limited, which is authorised and regulated by the Financial Conduct Authority. Calls may be monitored/recorded.


