Find the Best Mortgage Deals

Latest UK Interest Rate Forecasts: Will the Bank of England raise interest rates again on 17 December?

After the Bank of England raised interest rates to 4% on 5 November and Governor Andrew Bailey warned another increase may be needed, we examine the latest forecasts from economists and financial markets, and explain what they could mean for your mortgage.

Post updated: November 9th, 2026

UK interest rate forecast

KEY INFORMATION

Interest rates in 2026: at a glance

  • Current base rate: 4%, increased from 3.75% on 5 November 2026. This was the first rise since August 2023.
  • Next decision: 17 December 2026. 
  • 2026 and 2027 outlook: Andrew Bailey has signalled another increase may be needed unless inflation risks ease, but has cautioned against expecting a long series of increases. Financial markets have priced in three further rate rises. This would take the base rate to 4.75%. Economists generally expect fewer increases, with some predicting another rise in February followed by cuts later in 2027.
  • Main risk: Higher inflation driven by volatile energy prices and the continuing conflict in the Middle East. The Bank now forecasts CPI inflation will reach 4.9% in the second quarter of 2027.

Latest UK interest rate forecasts and news

  • The Bank of England increased interest rates from 3.75% to 4% on 5 November, its first rise in over three years. Eight members of the Monetary Policy Committee voted for the quarter-point increase and ninth member Catherine Mann voted for a larger half-point rise to 4.25%.
  • Governor Andrew Bailey signalled that another increase may be needed unless the risks to inflation ease. However, he cautioned against seeing November’s decision as the start of a long series of rises.
  • The next decision is on 17 December, but Bailey has not said when a further increase might come.
  • November’s rise was widely expected after September’s rise in inflation to 3.5%, up from 3.1% in August. The Bank’s November forecast now predicts inflation will reach 4.9% in the second quarter of 2027, driven largely by higher energy costs linked to the Middle East conflict.
  • However, there is a gap between what financial markets and economists expect to happen next. Speaking on 6 November, the Bank’s chief economist Huw Pill said financial markets were expecting three further interest rate rises. But he warned there could be more or fewer, depending on what happens to the economy.
  • He said the rise in energy prices has been smaller than in 2022, so a repeat of that year’s string of rate increases is unlikely. By spring 2027, the Bank expects a clearer picture of whether higher energy costs are pushing up other prices and wages. This will help it decide whether to raise interest rates further.
  • In contrast, economists generally expect fewer interest rate rises than financial markets. Bloomberg reported on 3 November that economists saw only a roughly 50% chance of another increase in early 2027 after an expected rise to 4% in November.
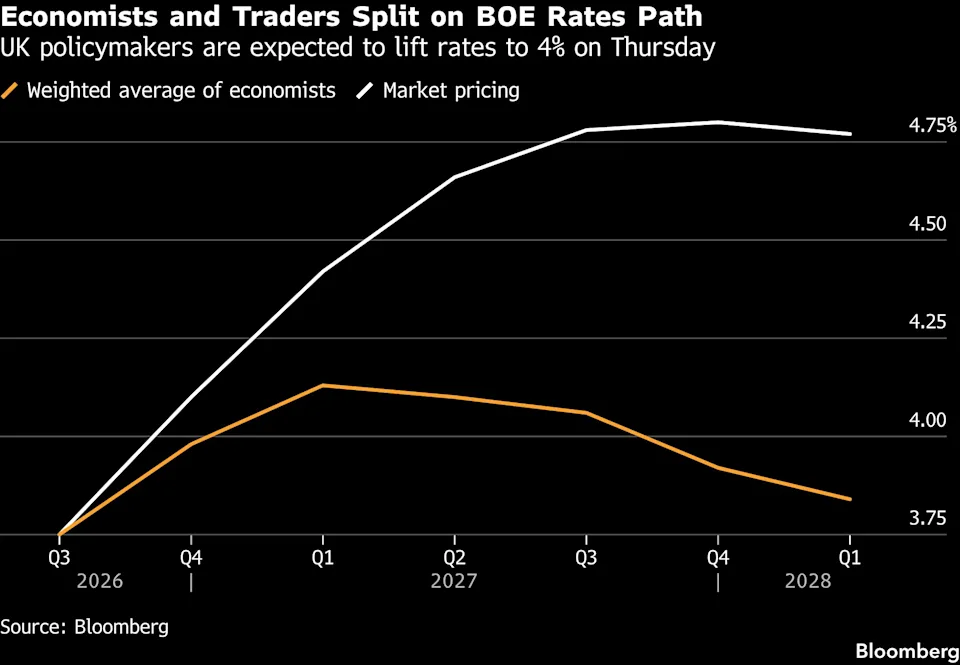
  • The Bloomberg chart below, published before the 5 November rate hike shows market pricing rising to around 4.75% in 2027, while economists forecast a smaller rise followed by cuts into early 2028.
Bank of England interest rate expectations: Bloomberg chart shows market pricing rising to around 4.75% in 2027, while economists forecast a smaller rise followed by cuts into early 2028.
Published with “Markets and Economists Are Divided Beyond a BOE Hike This Week”, by Tom Rees, Naomi Tajitsu and George Nixon, 3 November 2026.
  • “Everyone’s been expecting energy prices to come down and been basing their inflation and bank rate forecasts off that,” said Paul Dales, chief UK economist at Capital Economics. “That is why economists, by and large, don’t have many interest-rate hikes and have rates coming back down. But we’re in this world where if energy prices stay at these levels for another six months or so, then interest rates probably will be higher.”
  • Interest rate expectations have shifted sharply since the conflict in the Middle East began. Before it started, markets expected two rate cuts in 2026.

Will the Bank of England raise interest rates on 17 December?

Another rise is possible, but it’s not clear whether this is likely to be in December. Andrew Bailey’s comments suggest a further increase may be needed unless developments in the Middle East and energy prices ease the inflation risks.

The committee is divided about how much further rates may need to rise. Some members see a case for several increases, while others favour a more cautious approach.

Several economists’ forecasts published before November’s decision pointed to February 2027 for a further increase. However, these forecasts can change as new figures are released.

What UK interest rate forecasts mean for your mortgage

What markets expect to happen to interest rates has a direct impact on future fixed-rate mortgage pricing. Swap rates – which reflect market expectations for future interest rates – are the primary benchmark for pricing fixed-rate mortgages in the UK, although other factors such as competition also play a role.

If swap rates rise because markets expect higher interest rates, lenders typically increase mortgage rates. Conversely, falling swap rates can lead to cheaper fixed-rate mortgage deals. 

The outlook for interest rates has changed sharply since the conflict in the Middle East pushed up energy prices and increased concerns about inflation. Swap rates rose sharply earlier in October as markets increasingly expected UK interest rates to rise.

This prompted many lenders to increase their fixed mortgage rates, although some have since cut selected deals and average fixed rates have edged down slightly. These small reductions follow sharp increases in September and early October.

November’s base rate rise was widely expected and already largely reflected in fixed mortgage pricing. This helps explain why some new fixed deals have become slightly cheaper even as the base rate has increased.

What happens next will depend partly on whether markets change their expectations for December and 2027. 

If your mortgage deal ends in the next six months, consider reviewing your options now. You may be able to lock in a rate in advance and keep it under review in case a better deal becomes available before you need to switch.

What should you do if you have a mortgage?

  • On a fixed rate? Your payments won’t change until your deal ends, even if interest rates rise or fall.
  • On a tracker mortgage? Your rate will rise in line with November’s base rate increase. Your lender will confirm when your payments change and how much you’ll pay.
  • Remortgaging soon? If your current deal ends in the next six months, consider locking in a rate now to protect against the risk of mortgage rates rising further. You can then keep the rate under review.

Get fee-free mortgage advice from the award-winning expert advisers at Mortgage Advice Bureau. Compare deals or speak to an adviser today.

Need remortgage advice?

Get fee-free remortgage advice from the award-winning expert advisers at Mortgage Advice Bureau.

Get remortgage advice now

Your home may be repossessed if you do not keep up repayments on your mortgage. Please note some branches of Mortgage Advice Bureau may charge a fee for mortgage advice if you go direct. The fee is up to 1% but a typical fee is 0.3% of the amount borrowed. So make sure you use this site, this form or phone number for fee-free advice.

Expert view on interest rate forecasts and mortgages

HomeOwners Alliance’s mortgage expert Sarah Tucker says:
“If you’re on a tracker mortgage linked to the Bank Rate, your rate will rise in line with today’s increase, so your monthly payments will go up. For borrowers on fixed rate mortgages things work differently: they’re influenced by swap rates and market expectations, so lenders can change them before a Bank of England decision. Further rate rises – including this one – have been priced in already, which is one reason fixed rate mortgages sit higher.“

“The one silver lining is that last week’s Budget hasn’t caused the market disruption some feared, which is welcome. Swap rates have eased from their recent highs, although they remain above where they were a month ago.”

“But there are always external factors impacting the markets and the mortgage rates homeowners will pay. Recent government advice for homeowners to stockpile supplies in case of severe weather or cyber attacks is a reminder that we can’t control everything happening in the wider world. What we can do is get organised with our mortgage and seek advice early, rather than leave it until the last minute.”

Economists’ UK interest rate forecasts

Interest rate predictions are notoriously difficult at the best of times, but the complexity of the current situation in the Middle East makes it even harder.

Economists generally expect fewer further rate rises than financial markets have priced in. However, they remain divided about how many increases will be needed and when rates could start falling again.

Analysts responding to the 5 November announcement also differed on the outlook:

  • Madison Faller at JPMorgan told The Times: “Today’s move feels like a measured, credibility-preserving one rather than the start of an aggressive cycle.” She added: “On balance, more hikes may be needed, but the data likely needs to demand it.”
  • Neil Birrell at Premier Miton said: “The fall we have seen in the oil price is obviously welcome news, but high energy prices are baked into the system now.”
  • David Rees, chief economist at Schroders, said: “But this is not the start of an aggressive tightening campaign. Ultimately domestic inflation remains relatively well behaved, and there is still slack in the economy.”

However, what happens with interest rates next will depend on numerous factors. You can keep up to date by bookmarking our guide to best mortgage rates in the UK or signing up to our weekly newsletter.

Need to remortgage? Get fee-free mortgage advice from the award-winning expert advisers at Mortgage Advice Bureau.

Why did the Bank of England raise interest rates on 5 November 2026?

  • The November rise came amid renewed concerns about inflation. CPI inflation increased to 3.5% in September, up from 3.1% in August and above the Bank’s 2% target.
  • Although there is still limited evidence of higher energy costs feeding into wider price and wage increases, policymakers judged that the inflation pressure building up was enough to warrant action. Stronger-than-expected economic activity also supported the decision.
  • Raising interest rates makes borrowing more expensive and can encourage saving rather than spending, helping to reduce demand and bring inflation down.

When did the Bank of England last make an interest rate cut?

  • The Bank of England last cut UK interest rates in December 2025 to their lowest level in almost three years, marking the sixth interest rate cut since rates peaked at 5.25% in 2023 and 2024.
Bank of England Base Rate 2020-2026

When will UK mortgage rates come down?

Some lenders have cut selected fixed mortgage rates in recent days and average fixed rates have edged down slightly. However, average 2 and 5 year fixed rates remain close to 6%, following sharp increases in September and early October.

November’s base rate increase was widely expected and already largely reflected in fixed mortgage pricing. Whether fixed rates fall further will depend partly on how expectations change for December and 2027.

Whether mortgage rates come down again will depend largely on what happens to swap rates. If swap rates fall, fixed mortgage rates may follow, while further increases could push mortgage rates higher. With the outlook uncertain, lenders may continue to change their deals at short notice.

This unpredictable outlook comes as little surprise to the UK public. In our 2026 research, we found that around a quarter of Brits expect rates to rise (23%) and a similar proportion think they will fall (25%), while 28% expect them to stay the same and 24% are unsure.

But there are many factors at play, which makes an accurate mortgage rate forecast difficult to make. Read more in our guide on Mortgage rate predictions.

What are interest rates and why do they change?

  • The Bank of England’s base rate acts as a benchmark for the cost of borrowing money. As a general rule, when interest rates increase, so does the cost of borrowing on mortgages and other types of borrowing.
  • One major reason why the Bank moves rates up and down is to help control inflation. When inflation is high, the Bank may increase interest rates to try to bring it down by encouraging people to spend less and reduce demand. And once inflation is at or near its target, the Bank may hold or cut interest rates.
  • However, the Bank’s Monetary Policy Committee will assess a range of factors when deciding whether to change interest rates including jobs and wage data and external factors that can impact the economy. Government tax and spending decisions can also form part of the economic outlook. Read our guide to the Autumn Budget 2026 for what was announced and what it means for homeowners.

Get personalised advice by speaking to the award-winning expert advisers at Mortgage Advice Bureau. Compare deals or speak to an adviser today.

Need mortgage advice?

Get fee-free mortgage advice from the award-winning expert advisers at Mortgage Advice Bureau.

Get mortgage advice now

Your home may be repossessed if you do not keep up repayments on your mortgage. Please note some branches of Mortgage Advice Bureau may charge a fee for mortgage advice if you go direct. The fee is up to 1% but a typical fee is 0.3% of the amount borrowed. So make sure you use this site, this form or phone number for fee-free advice.

What’s happening with the UK inflation rate?

  • Figures released by the Office for National Statistics on 21 October showed that UK CPI inflation increased to 3.5% in September, which was higher than expected. This was up from 3.1% in August.
  • September’s figure was driven by higher transport costs, particularly motor fuel, the ONS said.
  • CPIH, which includes owner‑occupiers’ housing costs, increased to 3.6%, up from 3.3%, while RPI inflation came in at 3.9%, up from 3.4%.
  • The Bank of England’s November forecast puts CPI inflation at 4.9% in the second quarter of 2027. It then projects inflation will fall back towards its 2% target in 2028.
  • This is a forecast, not a certainty. The outlook is particularly sensitive to what happens to energy prices and the Middle East conflict.

When is the Bank of England’s next Monetary Policy Committee meeting?

Key Bank of England interest rate decision dates:

  • 17 December 2026
  • 4 February 2027
  • 18 March 2027
  • 29 April 2027

The Bank of England publishes a calendar of future committee meeting dates here.

Get fee-free mortgage advice from the award-winning expert advisers at Mortgage Advice Bureau.

UK interest rate forecast for the next 2, 3 and 5 years

Many people want to know the UK interest rate forecast for the next 5 years. However, long-term UK interest rate forecasts should be treated with caution. The Office for Budget Responsibility (OBR) bases its forecasts on market expectations for future interest rates, but these expectations can change significantly as economic conditions evolve.

For example, in its October 2026 Economic and Fiscal Outlook, the OBR’s economic forecast used market assumptions showing Bank Rate rising to just above 4.25% by mid-2027 and just above 4.5% by the end of its forecast period. These assumptions used market data from August, so they do not reflect the latest November expectations.

On 6 November, Huw Pill said financial markets were expecting three further rate rises, although there could be more or fewer. Three quarter-point increases would take the base rate from 4% to 4.75%. Economists generally expect fewer increases, with some forecasting cuts later in 2027.

That gap matters for mortgages because market expectations influence the swap rates lenders use to price fixed deals. However, neither market pricing nor economists’ forecasts can tell us with certainty where interest rates will be in two, three or five years.

Forecasts beyond 2027 are even more uncertain and could change significantly as the outlook for inflation and the economy develops.

What does ‘terminal rate’ mean?

The Bank of England’s terminal rate is the level interest rates are expected to reach at the end of a cycle of rate changes. This could be the peak of a rate-rising cycle or the lowest point of a rate-cutting cycle, before rates are held or change direction.

Interest rate changes’ impact on credit cards and loans

Other types of borrowing are affected in a similar way. If interest rates go up, borrowing can generally get more expensive, while when interest rates are cut, borrowing can generally get cheaper.

However, the amount you’ll pay on things like credit cards and loans will depend on a number of factors including your credit history.

Subscribe
Notify of
guest

18 Comments
Newest
Oldest Most Voted

Related Articles

for the latest news, advice and money saving offers

Latest News

Privacy Overview

This website uses cookies so that we can provide you with the best user experience possible. Cookie information is stored in your browser and performs functions such as recognising you when you return to our website and helping our team to understand which sections of the website you find most interesting and useful.

Strictly Necessary Cookies

Strictly Necessary Cookies are required for the website to function correctly.

Analytics & Website Improvement

We use analytics technologies to understand how visitors use our website, measure the effectiveness of our content and services, and improve the overall user experience. This information helps us identify popular pages, improve website performance, and make our services more useful. You can disable these technologies.

Advertising & Personalisation

These technologies help us measure the effectiveness of advertising, understand which marketing campaigns generate enquiries, and show more relevant advertising on other websites and platforms.